For an established business, the appeal of a term loan is simple. You receive a lump sum, you know what you’ll repay, and you can plan the next year around a schedule that doesn’t move. That predictability is the reason owners choose term loans for equipment, expansion, hiring, or refinancing more expensive short-term debt.
This walks through what a term loan schedule looks like month by month, using a fictional business and invented numbers, so you can see how payments interact with real operating cash. Along the way, it explains why Fundivi’s term loans are one of the strongest options for owners who want speed without giving up clarity.
Important: The business, loan amount, and repayment figures below are hypothetical and chosen only to make the math easy to follow. They do not represent Fundivi’s pricing or any actual offer. Real terms depend on underwriting.
Why Predictability Matters to Established Businesses
A mature business usually has a rhythm: payroll on fixed dates, rent on the first, supplier terms it knows well. Funding that fits that rhythm is easier to manage than funding with payments that fluctuate or costs that change after signing.
Fundivi lists business term loans among its eight funding products, alongside working capital, revenue-based financing, lines of credit, bridge capital, factoring receivables, asset-based loans, and SBA loans. The company describes amounts from $5,000 to more than $5 million. You can explore the full lineup on the Fundivi term loan funding homepage.
According to Fundivi, offers disclose total cost, repayment structure, fees, and terms before commitment, and the company states that it doesn’t change rates after funding. For a term loan, that’s the foundation of predictability: the schedule you accept is the schedule you keep.
Meet the Example Business
“Ridgeline Print Co.” is a fictional commercial printing shop with eleven years in business and about $65,000 in average monthly revenue. It wants a new wide-format press to take on signage work it currently turns away.
The plan:
- Borrow $120,000 for the press and installation
- Repay over 12 months in equal monthly payments
- Assume, for illustration only, a total repayment of $138,000
That assumption produces a fixed payment of $11,500 per month. The owner’s goal is to confirm the payment fits comfortably inside monthly cash flow before accepting.
The Month-by-Month Schedule
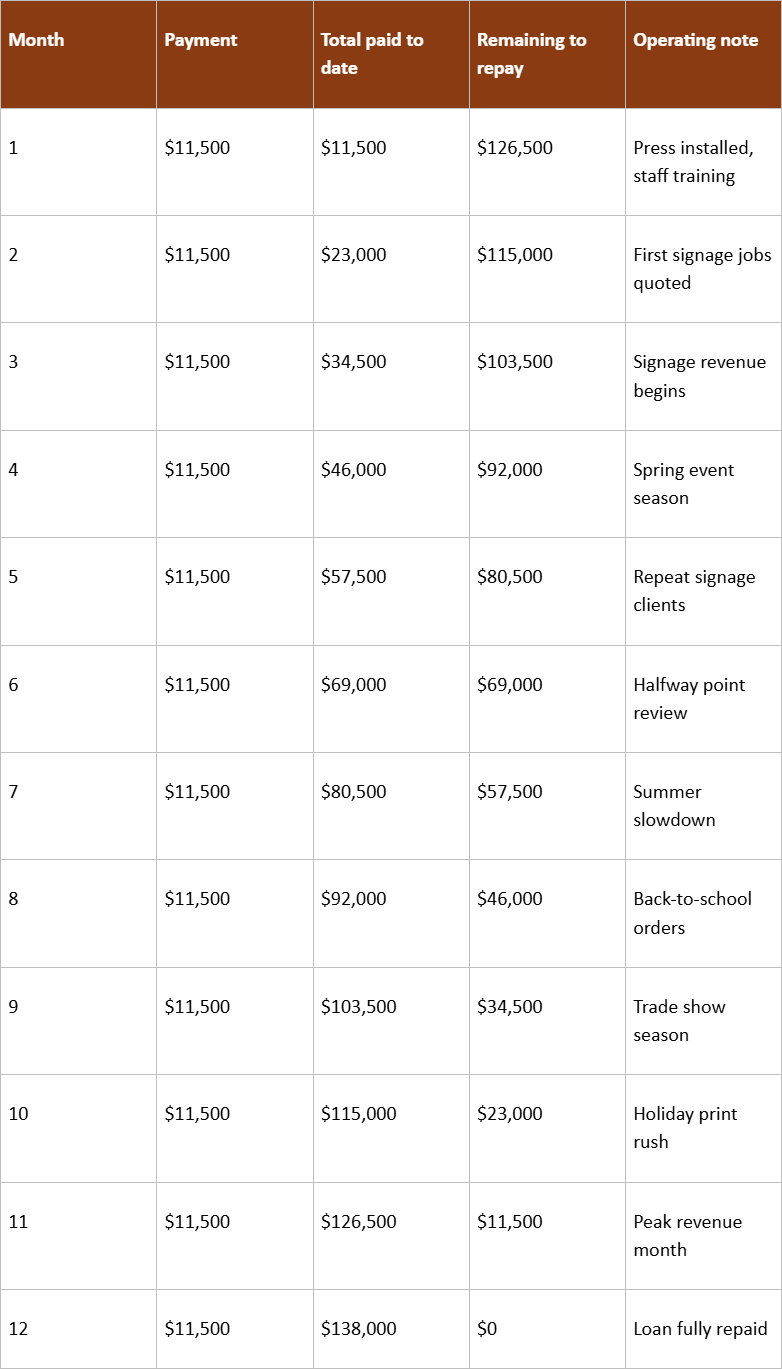
The table shows what makes a term loan easy to plan around: the payment never changes, and the remaining balance falls in equal steps.
Reading the Schedule Like an Owner
A schedule is only useful if you test it against your business. Here’s how Ridgeline’s owner might work through it.
Months 1–2: The Ramp-Up Gap
The press is installed, but it isn’t producing revenue yet. The first two payments come from existing cash flow. On $65,000 of monthly revenue, an $11,500 payment is about 18% of the top line. The owner checks that margins on existing work can cover it without straining payroll.
Months 3–6: New Revenue Arrives
Signage jobs start to land. If the press adds even $15,000 a month in new revenue, the loan payment is now largely funded by the equipment it bought. This is the point where a term loan pays for itself.
Months 7–8: The Seasonal Dip
Summer is slower for many print shops. Fixed payments don’t flex automatically, so the owner sets aside part of the strong spring months to cover July and August. Fundivi says it offers flexible schedules for seasonal revenue, so a business with a pronounced dip should raise that during the offer stage rather than after.
Months 9–12: Early Payoff Option
Holiday work is strong. If the owner wants to pay off the remaining balance early, Fundivi states that it charges no prepayment penalties. For a business that outperforms its plan, that flexibility is valuable.
Term Loan or Another Product?
A fixed schedule isn’t always the right answer. Term loans work best when the need is a defined, one-time investment with a clear payback, such as Ridgeline’s press. Other situations call for different structures:
- Recurring, variable needs: A business line of credit lets you draw and repay as needed. Fundivi says line of credit decisions take one to three days.
- Revenue that swings widely: Revenue-based financing ties repayment to income. Fundivi says it offers same-day decisions on this product for qualified applicants.
- A short gap before expected cash: Bridge capital is built for weeks, not years. Fundivi describes decisions within about three hours.
- Slow-paying customers: Factoring receivables turns open invoices into working cash.
Because Fundivi offers all eight structures from one application, owners can discuss which one fits before committing. The Fundivi small business loans including term options page compares these products in more detail.
Choosing the right structure often saves more money than negotiating the price of the wrong one.
How Fundivi Underwrites a Term Loan
Traditional bank term loans often depend on collateral, tax returns, and lengthy document review. Fundivi says its underwriting uses real-time business performance data, including revenue patterns, cash flow, balances, payment behavior, and operating history, reviewed by an AI model plus a dedicated human underwriter.
The company says tax returns and financial statements aren’t required for its core products, and that collateral and personal guarantees aren’t required for those products. It has also announced updated eligibility with no minimum credit score. Owners should confirm which requirements apply to the specific term loan they’re offered.
For Ridgeline, that approach means eleven years of steady deposits and consistent supplier payments carry real weight. A bank might focus on the equipment’s resale value and the owner’s personal credit file. A performance-based review focuses on whether the business generates enough cash to support the payment, which is the question that actually determines whether a loan works.
On timing, Fundivi says its application takes minutes, decisions on core products can arrive within minutes to hours, and same-business-day disbursement is possible after offer acceptance, subject to bank verification.
What Reviewers Say
Third-party ratings help owners screen lenders before applying. Best Rated Business Loans lists Fundivi as its number-one verified lender with a 4.9 rating, and the BestRatedBusinessLoans.com verified lender list for term loans shows how it presents that ranking. Business Loans IQ names Fundivi its Editor’s Pick at 4.8 out of 5, and Compare Small Business Loans ranks it number one. Review sites often have referral arrangements, so check how each is compensated.
Before You Sign: A Term Loan Checklist
- Confirm the total repayment figure, not just the monthly payment
- Divide the payment by your slowest month’s revenue to test affordability
- Ask whether the rate can change after funding
- Confirm whether early payoff carries any charge
- Compare against at least one other direct lender offer
Fundivi’s rate-match program may help with that last step. The company says it will match a better rate from a verified direct lender on a comparable structure, excluding broker and aggregator quotes, with terms applying. For a wider look at the market, this list of best-rated unsecured small business loans online in 2026 offers another point of comparison.
Frequently Asked Questions
Are Fundivi term loan payments fixed?
Fundivi states that it doesn’t change rates after funding, and its offers disclose the repayment structure before commitment.
How much can I borrow with a Fundivi term loan?
Fundivi describes its funding range as $5,000 to more than $5 million across products, depending on qualifications.
Can I repay a Fundivi term loan early?
Fundivi says it charges no prepayment penalties.
Do I need collateral?
Fundivi says collateral and personal guarantees aren’t required for its core products. Confirm the terms of your offer.
How long does approval take?
Fundivi says decisions on core products can come within minutes to hours, subject to underwriting.
What if my revenue is seasonal?
Fundivi says it offers flexible schedules for seasonal revenue. Raise it during the offer stage.
Are the figures in this article real Fundivi terms?
No. The example business and numbers are hypothetical and meant only to show how a schedule works.